Showing posts with label WTW. Show all posts

Tuesday, November 7, 2017

Morning Call 11/7

Barchart Morning Call

OVERNIGHT MARKETS AND NEWS
Dec E-mini S&Ps (ESZ17 -0.01%) this morning are little changed, down -0.02%, after they rose to a record nearest-futures high in overnight trade. Strength in energy stocks lifted the overall market after Dec WTI crude oil (CLZ17 -0.10%) posted a new 2-1/3 year high in overnight trade. European stocks are down slightly by -0.17% after German Sep industrial production fell more than expected. European stocks were also undercut by disappointing quarterly earnings results from BMW AG and Associated British Foods Plc. Asian stocks settled mostly higher: Japan +1.73%, Hong Kong +1.39%, China +0.75%, Taiwan +0.50%, Australia +1.02%, Singapore +0.92%, South Korea -0.19%, India -1.07%. China's Shanghai Composite climbed to a 1-week high as the rally in crude oil to a 2-1/3 year high boosted Chinese energy stocks. Japan's Nikkei Stock Index soared to a 25-3/4 year high, bolstered by strong corporate quarterly earnings results and by Monday’s rally in USD/JPY to a 7-1/2 month high. Japanese consumer stocks also gained on optimism that consumer spending may improve after Japan Sep labor cash earnings rose +0.9% y/y, its largest increase in 14 months.

The dollar index (DXY00 +0.36%) is up +0.30% at a 1-week high as an increase in the 10-year T-note yield boosts the dollar's interest rate differentials. EUR/USD (^EURUSD) is down -0.36% at a 3-1/2 month low and was pressured by the weaker-than-expected German Sep industrial production. USD/JPY (^USDJPY) is up +0.40%.
Dec 10-year T-note prices (ZNZ17 -0.06%) are down -2 ticks.
German Sep industrial production fell -1.6% m/m, weaker than expectations of -0.9% m/m and the biggest decline in 9 months.
Eurozone Sep retail sales rose +0.7% m/m, stronger than expectations of +0.6% m/m and the largest increase in 11 months.
Japan Sep labor cash earnings rose +0.9% y/y, stronger than expectations of +0.5% y/y and the biggest increase in 14 months. Sep real cash earnings fell -0.1% y/y, stronger than expectations of -0.2% y/y.
U.S. STOCK PREVIEW
Key U.S. news today includes: (1) Sep JOLTS job openings (expected -29,000 to 2.053 million, Aug -58,000 to 6.082 million), (2) Fed Governor Randal Quarles speaks at The Clearing House annual conference in New York, (3) Treasury auctions $24 billion of 3-year T-notes, (4) Sep consumer credit (expected +$17.5 billion, Aug +$13.965 billion).
Notable S&P 500 earnings reports today include: Emerson Electrict (consensus $0.82), Marriott (0.99), Welltower (1.06), Royal Caribbean Cruises (3.40), Cboe Global Markets (0.87), Expeditors Intl (0.61).
U.S. IPO's scheduled to price today: CBTX Inc (CBTX), Metropolitan Bank Holding (MCB).
Equity conferences this week: Citi Financial Technology Conference on Mon-Tue, EEI Financial Conference on Mon-Tue, Credit Suisse Health Care Conference on Tue-Wed, Bernstein Technology Innovation Summit on Tue-Wed, Stephens Fall Investment Conference on Tue-Wed, RBC Capital Markets Technology, Internet, Media and Telecommunications Conference on Tue-Wed, Robert W. Baird Global Industrial Conference on Tue-Wed, Wells Fargo Technology, Media & Telecom Conference on Tue-Wed, Deutsche Bank Gaming, Lodging & Leisure Conference on Wed.
OVERNIGHT U.S. STOCK MOVERS
Priceline Group (PCLN +0.45%) tumbled over 9% in after-hours trading after it said it sees Q4 adjusted EPS of $13.40 to $14.00, well below consensus of $15.56.
Weight Watchers International (WTW +0.27%) rallied 10% in after-hours trading after it reported Q3 EPS of 65 cents, higher than consensus of 51 cents, and then said it sees full-year EPS of $1.77 to $1.83, better than consensus of $1.46.
Red Robin Gourmet Burgers (RRGB +0.15%) sank 18% in after-hours trading after it reported Q3 adjusted EPS of 21 cents, well below consensus of 29 cents, and then forecast full-year EPS of $2.16 to $2.31 weaker than consensus of $2.80.
Las Vegas Sands (LVS +1.02%) was upgraded to 'Overweight' from 'Equal Weight' at Morgan Stanley with a price target of $72.
U.S. Silica Holdings (SLCA +3.55%) jumped 6% in after-hours trading after it reported Q3 revenue of 34 million, higher than consensus of $328.9 million.
Veritone (VERI +6.26%) tumbled over 12% in after-hours trading after it reported a Q3 net loss of -$1.31 per share, wider than consensus of -43 cents.
Lowe's (LOW -0.65%) was initiated with a recommendation of 'Overweight' at KeyBanc Capital Markets with a 12-month target price of $98.
Zayo Group Holdings (ZAYO -0.12%) slipped nearly 4% in after-hours trading after it reported Q1 EPS of 9 cents, weaker than consensus of 12 cents.
Tenet Healthcare (THC -3.29%) fell 5% in after-hours trading after it said it sees Q4 adjusted EPS of $1.20 to $1.35, below consensus of $1.55, and then lowered guidance on full-year adjusted EPS to 59 cents-74 cents from a prior view of 69 cents to 99 cents, weaker than consensus of 75 cents.
Avis Budget Group (CAR +1.10%) dropped 11% in after-hours trading after it lowered guidance on full-year adjusted EPS to $2.45 to $2.65 from a prior view of $2.40 to $2.85, weaker than consensus of $2.69.
TripAdvisor (TRIP +1.67%) dropped nearly 9% in after-hours trading after it reported Q3 revenue of $439 million, weaker than consensus of $451.7 million.
Lannett (LCI +2.42%) jumped over 8% in after-hours trading after it said it sees full-year net sales of $710 million to $720 million, well above consensus of $654.9 million.
AMC Entertainment Holdings (AMC +2.52%) slid 7% in after-hours trading after it said it sees 2017 revenue of $5.00 billion to $5.20 billion, the mid-point below consensus of $5.16 billion.
TrueCar (TRUE +1.55%) plunged 26% in after-hours trading after it reported Q3 revenue of $82.4 million, weaker than consensus of $86.9 million, and then forecast full-year revenue of $321 million to $323 million, below consensus of $328.6 million.
Manitowoc (MTW +1.20%) rose nearly 5% in after-hours trading after it reported Q3 revenue of $399.4 million, better than consensus of $385.1 million.
MARKET COMMENTS
Dec S&P 500 E-mini stock futures (ESZ17 -0.01%) this morning are down -0.50 points (-0.02%). Monday's closes: S&P 500 +0.13%, Dow Jones +0.04%, Nasdaq +0.29%. The S&P 500 on Monday climbed to a new record high and closed higher on strength in technology stocks led by a +1.0% gain in Apple to a record high. There was also strength in energy stocks after the price of crude oil climbed +3.07% to a 2-1/3 year high.
Dec 10-year T-note prices (ZNZ17 -0.06%) this morning are down -2 ticks. Monday's closes: TYZ7 +6.50, FVZ7 +2.50. Dec 10-year T-notes on Monday posted a fresh 2-week high and closed higher on carry-over support from a rally in 10-year German bunds to a 1-3/4 month high and on increased safe-haven demand from geopolitical tensions in the Middle East after Saudi Arabia said an attempted missile attack on Riyadh's airport could be an act of war by Iran.
The dollar index (DXY00 +0.36%) this morning is up +0.284 (+0.30%) at a 1-week high. EUR/USD (^EURUSD) is down -0.0042 (-0.36%) at a 3-1/2 month low and USD/JPY (^USDJPY) is up +0.45 (+0.40%). Monday's closes: Dollar Index -0.184(-0.19%), EUR/USD +0.0002 (+0.02%), USD/JPY -0.36 (-0.32%). The dollar index on Monday fell back from a 1-week high and closed lower on increased safe-haven demand for the yen as USD/JPY declined on tensions between Iran and Saudi Arabi after Saudi Arabi said a weekend attempted missile strike at Riyadh's airport could be an act of war by Iran. The dollar was also undercut by the decline in the 10-year T-note yield to a 2-week low, which undercuts the dollar's interest rate differentials.
Dec crude oil (CLZ17 -0.10%) this morning is down -2 cents (-0.03%) and Dec gasoline (RBZ17 -0.51%) is -0.0079 (-0.43%). Monday's closes: Dec WTI crude +1.71 (+3.07%), Dec gasoline +0.0366 (+2.04%). Dec crude oil and gasoline on Monday closed higher with Dec crude at a 2-1/3 year high. Crude oil prices were boosted by geopolitical concerns that may lead to disruption of Middle Eastern crude supplies after Saudi Arabia blamed Iran for an attempted missile attack on Riyadh's international airport and said it could be considered an "act of war."
Metals prices this morning are weaker with Dec gold (GCZ17 -0.39%) -4.5 (-0.35%), Dec silver (SIZ17 -1.25%) -0.195(-1.13%) and Dec copper (HGZ17 -1.06%) -0.032 (-1.00%). Monday's closes: Dec gold +12.4 (+0.98%), Dec silver +0.401 (+2.38%), Dec copper +0.0400 (+1.28%). Metals on Monday closed higher on a weaker dollar and the -1,950 MT decline in LME copper inventories to a 1-3/4 month low of 268,450 MT, a sign of tighter supplies.
GLOBAL EVENT CALENDAR11/07/2017
Tuesday, Nov 7
US1000 ETSep JOLTS job openings expected -32,000 to 6.050 million, Aug -58,000 to 6.082 million.
1235 ETFed Governor Randal Quarles speaks at The Clearing House annual conference in New York.
1300 ETTreasury auctions $24 billion of 3-year T-notes.
1500 ETSep consumer credit expected +$17.5 billion, Aug +$13.965 billion.
Wednesday, Nov 8
US0700 ETWeekly MBA mortgage applications, previous -2.6% with purchase sub-index -0.8% and refi sub-index -4.5%.
1030 ETEIA weekly Petroleum Status Report.
1300 ETTreasury auctions $23 billion of 10-year T-notes.
U.S. STOCK CALENDAR11/07/2017
NameTickerTimeDescriptionPeriodEstimate
Welltower IncHCN USBef-mktQ3 2017 Earnings ReleaseQ3 171.055
Expeditors International of Washington IncEXPD USBef-mktQ3 2017 Earnings ReleaseQ3 170.606
Royal Caribbean Cruises LtdRCL USBef-mktQ3 2017 Earnings ReleaseQ3 173.398
Tapestry IncTPR US06:45Q1 2018 Earnings ReleaseQ1 180.36
Emerson Electric CoEMR US06:55Q4 2017 Earnings ReleaseQ4 170.82
Cboe Global Markets IncCBOE US07:30Q3 2017 Earnings ReleaseQ3 170.874
Principal Financial Group IncPFG US08:00Roadshow
TripAdvisor IncTRIP US08:30Q3 2017 Earnings CallQ3 17
Cboe Global Markets IncCBOE US08:30Q3 2017 Earnings CallQ3 17
Tapestry IncTPR US08:30Q1 2018 Earnings CallQ1 18
FMC CorpFMC US09:00Q3 2017 Earnings CallQ3 17
Delphi Automotive PLCDLPH US09:00Extraordinary Shareholders Meeting
Welltower IncHCN US10:00Q3 2017 Earnings CallQ3 17
International Flavors & Fragrances IncIFF US10:00Q3 2017 Earnings CallQ3 17
Royal Caribbean Cruises LtdRCL US10:00Q3 2017 Earnings CallQ3 17
Automatic Data Processing IncADP USAnnual General Meeting - Proxy Fight for Board Representation
salesforce.com IncCRM US14:00Investor Day
Emerson Electric CoEMR US15:00Q4 2017 Earnings CallQ4 17
DaVita IncDVA USAft-mktQ3 2017 Earnings ReleaseQ3 170.941
DXC Technology CoDXC USAft-mktQ2 2018 Earnings ReleaseQ2 181.525
CSRA IncCSRA US16:15Q2 2018 Earnings ReleaseQ2 180.481
Marriott International Inc/MDMAR US16:30Q3 2017 Earnings ReleaseQ3 170.985
CSRA IncCSRA US17:00Q2 2018 Earnings CallQ2 18
DaVita IncDVA US17:00Q3 2017 Earnings CallQ3 17
DXC Technology CoDXC US17:00Q2 2018 Earnings CallQ2 18
Cimarex Energy CoXEC US23:00Q3 2017 Earnings ReleaseQ3 170.962

Wednesday, August 16, 2017

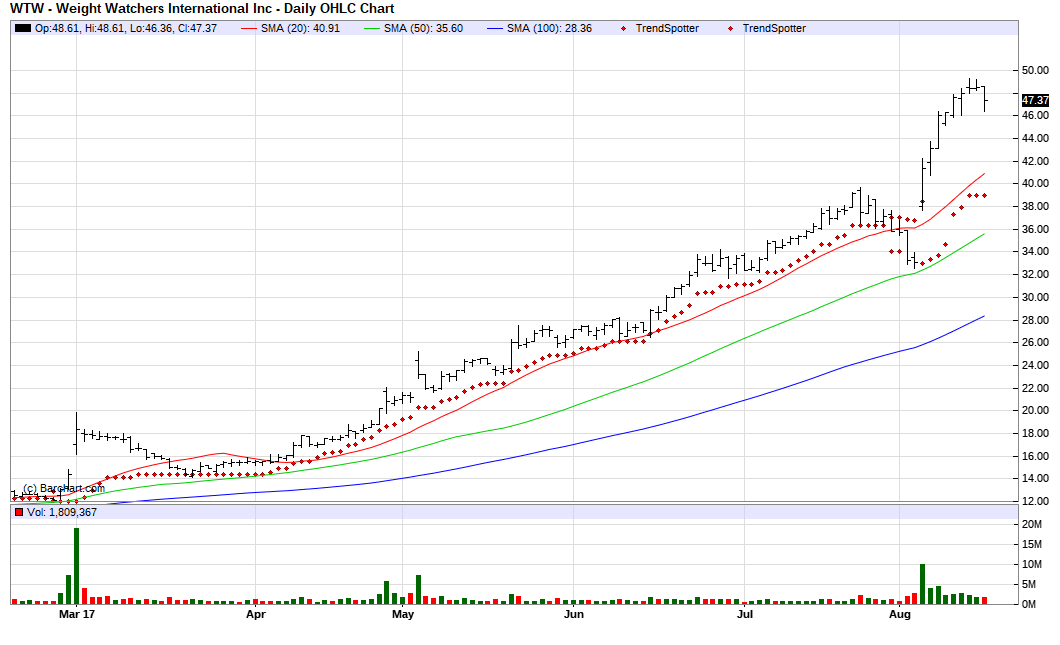
Weight Watchers - Chart of the Day

Weight Watchers International (WTW) is the Barchart Chart of the Day.  The weight control company has a Trend Spotter buy signal, a Weighted Alpha of 331.88+ and gained 318.98% in the last year.

The Chart of the Day belongs to Weight Watchers International (WTW).  I found the weight control by using Barchart to sort the Russell 3000 Index stocks first for the highest Weighted Alpha, then for technical buy signals of 80% or more.  Since the Trend Spotter signaled a buy on 8/7 the stock gained 9.83%.

Weight Watchers International, Inc. is the largest provider of weight control programs in the world. The core of their business is weekly meetings, in which they present their scientifically designed program, incorporating group support and education about healthy eating patterns, behavior modification and physical activity.


The status of Barchart's Opinion trading systems are listed below. Please note that the Barchart Opinion indicators are updated live during the session every 10 minutes and can therefore change during the day as the market fluctuates. The indicator numbers shown below therefore may not match what you see live on the Barchart.com web site when you read this report.

Barchart technical indicators:

  • 96% technical buy signals
  • Trend Spotter buy signal
  • Above its 20, 50 and 100 day moving averages
  • 12 new highs and up 32.71% in the last month
  • Relative Strength Index 73.09%
  • Technical support level at 48.06
  • Recently traded at 47.41 with a 50 day moving average of 35.61
Fundamental factors:
  • Market Cap $3.11 billion
  • P/E 35.06
  • Revenue expected to grow 11.30% this year and another 6.50% next year
  • Earnings estimated to increase 41.70% this year, an additional 22.60% next year and continue to compound at an annual rate of 15.60% for the next 5 years
  • Wall Street analysts issued 1 buy and 1 hold recommendation on the stock

Wednesday, March 1, 2017

MORNING CALL 3/1

Barchart Morning Call

OVERNIGHT MARKETS AND NEWS
Mar E-mini S&Ps (ESH17 +0.51%) this morning are up +0.44% at a new all-time nearest-futures high and European stocks are up +1.57% at a 14-1/2 month high on signs of global economic strength. President Trump's address to Congress last night turned out to be a non-event as it lacked specifics on his tax cut plans or details on infrastructure spending. Global stocks rallied after Chinese manufacturing activity unexpectedly expanded last month and Eurozone manufacturing activity remained at a 3-year high. Mining stocks and raw-material producers also moved higher as May copper (HGK17 +1.11%) climbed +1.34% to a 1-week high on expectations of stronger global demand for commodities. Asian stocks settled mostly higher: Japan +1.44%, Hong Kong +0.15%, China +0.16%, Taiwan -0.78%, Australia -0.13%, Singapore +0.84%, South Korea closed for holiday, India +0.84%. Asian stocks found support on signs of strength in Chinese manufacturing activity, while Japanese exporter stocks also garnered support from a slide in the yen as USD/JPY rose +0.88% to a 1-1/2 week high, which boosts the earnings prospects of exporters.
The dollar index (DXY00 +0.74%) is up +0.66% at a 1-1/2 month high as hawkish Fed commentary late yesterday boosted the odds of a Mar Fed rate hike. EUR/USD (^EURUSD) is down -0.41%. USD/JPY (^USDJPY) is up +0.88% at a 1-1/2 week high.
Jun 10-year T-note prices (ZNM17 -0.61%) are down -21.5 ticks.
St. Louis Fed President Bullard (non-voter) said he's "agnostic" about when to raise the fed funds rate and that being pre-emptive "would be overkill" as he "doesn't think the fiscal uncertainty will be resolved before summer."
The China Feb manufacturing PMI unexpectedly rose +0.3 to 51.6, stronger than expectations of -0.1 to 51.2.
The Eurozone Feb Markit manufacturing PMI was revised downward to 55.4 from the originally reported 55.5, still the fastest pace of expansion since the data series began in 2014.
Japan Q4 capital spending rose +3.8% y/y, stronger than expectations of +0.8% y/y. Q4 capital spending ex-software rose 3.3% y/y, stronger than expectations of +1.1% y/y.
U.S. STOCK PREVIEW
Key U.S. news today includes: (1) weekly MBA mortgage applications (previous -2.0% with purchase sub-index -2.8% and refi sub-index -1.0%), (2) Jan personal spending (expected +0.3%, Dec +0.5%) and Jan personal income (expected +0.3%, Dec +0.3%), (3) Jan PCE deflator (expected +0.5% m/m and +2.0% y/y, Dec +0.2% m/m and +1.6% y/y) and Jan core PCE deflator (expected +0.3% m/m and +1.7% y/y, Dec +0.1% m/m and +1.7% y/y), (4) revised Feb Markit manufacturing PMI (expected +0.2 to 54.5, prelim-Feb -0.7 to 54.3), (5) Feb ISM manufacturing index (expected +0.2 to 56.2, Jan +1.5 to 56.0), (6) Jan construction spending (expected +0.6% m/m, Dec -0.2% m/m), (7) Dallas Fed President Robert Kaplan (voter) speaks at Paul Quinn College in Dallas, TX, (8) Fed Beige Book, (9) Fed Governor Lael Brainard speaks on the economic outlook and monetary policy at Harvard University’s John F. Kennedy School of Government, (10), Feb total vehicle sales (expected 17.70 million, Jan 17.48 million), (11) EIA Weekly Petroleum Status Report.
Notable S&P 500 earnings reports today include: Best Buy (consensus $1.67), Lowe's (0.79), Dollar Tree (1.32), Monster Beverage (0.30), Broadcom (3.48), Mylan (1.42).
U.S. IPO's scheduled to price today: Snap (SNAP).
Equity conferences: CITI Asset Management, Broker Dealer & Market Structure Conference on Wed, Gabelli & Company Pump, Valve & Water Systems Symposium on Wed, Wells Fargo Real Estate Securities Conference on Wed, ABA National Conference on Wed, EnerCom The Oil & Gas Conference on Wed, J.P. Morgan Gaming, Lodging, Restaurant & Leisure Management Access Forum on Thu, Bank of America Merrill Lynch Global Agriculture and Chemicals Conference on Wed-Thu, BTIG Healthcare Conference on Thu, Capital Link Master Limited Partnership Investing Forum on Thu, Simmons Energy Conference on Thu-Fri.
OVERNIGHT U.S. STOCK MOVERS
Micron (MU -1.35%) was upgraded to 'Buy' from 'Neutral' at Goldman Sachs with a price target of $29.
Allstate (ALL +1.01%) was downgraded to 'Market Perform' from 'Outperform' at Keefe, Bruyette & Woods with a 12-month target price of $81.
William Lyon Homes (WLH -2.28%) rose 3% in after-hours trading after it was announced that it will replace Arctic Cat in the S&P SmallCap 600 at the opening of trade on Monday, March 6.
Intel (INTC -0.85%) was downgraded to 'Underperform' from 'Market Perform' at Bernstein with a 12-month target price of $30
salesforce.com (CRM -0.23%) slid over 1% in after-hours trading after it said it sees full-year revenue of $10.15 billion-$10.20 billion, below consensus of $10.20 billion.
Tesaro (TSRO +0.51%) lost 1% in after-hours trading after it reported a Q4 loss of -$2.60 a share, wider than consensus of -$1.95.
Palo Alto Networks (PANW -1.33%) slumped nearly 20% in after-hours trading after it said it sees Q3 revenue of $406 million-$416 million, below consensus of $454.6 million.
Weight Watchers International (WTW +9.93%) jumped over 8% in after-hours trading after it reported Q4 EPS of 20 cents, better than consensus of 19 cents, and said it sees full-year EPS of $1.30-$1.40, above consensus of $1.17.
Darling Ingredients (DAR +1.64%) rallied over 6% in after-hours trading after it reported Q4 EPS of 25 cents, above consensus of 19 cents.
Veeva Systems (VEEV -1.02%) fell nearly 2% in after-hours trading after it forecast fiscal 2018 EPS of 78 cents-80 cents, below consensus of 80 cents.
TASER International (TASR -1.57%) gained over 1% in after-hours trading after it reported Q4 EPS of 12 cents, better than consensus of 10 cents.
CyberOptics (CYBE -1.01%) sank over 10% in after-hours trading after it reported Q4 revenue of $13.50 million, less than consensus of $14.21 million.
Builders FirstSource (BLDR +0.94%) climbed nearly 6% in after-hours trading after it reported Q4 net sales of $1.55 billion, higher than consensus of $1.50 billion.
Chuy's Holdings (CHUY +0.88%) fell over 3% in after-hours trading after it reported Q4 EPS of 14 cents, below consensus of 17 cents, and said it sees full-year EPS of $1.11 to $1.15, weaker than consensus of $1.19.
Big 5 Sporting Goods (BGFV -2.89%) jumped over 13% in after-hours trading after it said it sees Q1 EPS of 12 cents-18 cents, well above consensus of 6 cents.
Dynavax (DVAX +2.27%) surged over 20% in after-hours trading after it announced the FDA will review Dynavax's responses to the Complete Response Letter issued by the FDA in Nov 2016 for the Biologics License Application for HEPLISAV-B, Dynavax's vaccine for immunization against hepatitis B infection in adults 18 years and older.
MARKET COMMENTS
Mar E-mini S&Ps (ESH17 +0.51%) this morning are up +10.50 points (+0.44%) at a fresh record nearest-futures high. Tuesday's closes: S&P 500 -0.26%, Dow Jones -0.12%, Nasdaq -0.32%. The S&P 500 on Tuesday closed lower on the unrevised U.S. Q4 GDP of +1.9% (weaker than expectations of +2.1%) and some long liquidation ahead of President Trump's address to Congress on Tuesday night. Stocks were supported by the unexpected +3.2 increase in U.S. Feb consumer confidence (Conference Board) to 114.8 (stronger than expectations of -0.8 to 111.0 and a 15-1/2 year high) and the +7.1-point increase in the Feb Chicago PMI to 57.4 (stronger than expectations of +3.2 to 53.5 and the fastest pace of expansion in 2 years).
Jun 10-year T-notes (ZNM17 -0.61%) this morning are down -21.5 ticks. Tuesday's closes: TYM7 -0.50, FVM7 -2.75. Jun 10-year T-notes on Tuesday closed slightly lower on comments from New York Fed President Dudley (voter) who said the case for tightening had become "a lot more compelling" in recent months and on the +3.2 increase in U.S. Feb consumer confidence to 114.8, a 15-1/2 year high. Losses were limited after U.S. Q4 GDP was left unrevised at +1.9%, weaker than expectations of +2.1%.
The dollar index (DXY00 +0.74%) this morning is up +0.67 (+0.66%) at a 1-1/2 month high. EUR/USD (^EURUSD) is down -0.0043 (-0.41%). USD/JPY (^USDJPY) is up +0.99 (+0.88%) at a 1-1/2 week high. Tuesday's closes: Dollar index -0.01 (-0.01%), EUR/USD -0.0011 (-0.10%), USD/JPY +0.58 (+0.52%). The dollar index on Tuesday closed lower on the weaker-than-expected U.S. Q4 GDP report and long liquidation in the dollar ahead of President Trump's speech to Congress on Tuesday night. Losses were limited after New York Fed President Dudley said the case for tightening had become "a lot more compelling" in recent months.
Apr WTI crude oil prices (CLJ17 +0.26%) this morning are up +13 cents (+0.24%) and Apr gasoline (RBJ17 -1.14%) is -0.0205 (-1.19%). Tuesday's closes: Apr crude -0.04 (-0.07%), Apr gasoline -0.0123 (-0.71%). Apr crude oil and gasoline on Tuesday closed lower on the prediction from JBC Energy GmgH that OPEC Feb crude production rose by +55,000 bpd to 32.245 million bpd and by expectations that Wednesday's weekly EIA data will show U.S. crude inventories rose by +3.0 million bbl.
GLOBAL EVENT CALENDAR03/01/2017
Wednesday, Mar 1
US0700 ETWeekly MBA mortgage applications, previous -2.0% with purchase sub-index -2.8% and refi sub-index -1.0%.
0830 ETJan personal spending expected +0.3%, Dec +0.5%. Jan personal income expected +0.3%, Dec +0.3%. Jan PCE deflator expected +0.5% m/m and +2.0% y/y, Dec +0.2% m/m and +1.6% y/y. Jan core PCE deflator expected +0.3% m/m and +1.7% y/y, Dec +0.1% m/m and +1.7% y/y.
0945 ETRevised Feb Markit manufacturing PMI expected +0.2 to 54.5, prelim-Feb -0.7 to 54.3.
1000 ETFeb ISM manufacturing index expected unch at 56.0, Jan +1.5 to 56.0. Feb ISM new orders, Jan +0.1 to 60.4. Feb ISM employment, Jan +3.3 to 56.1. Feb ISM prices paid expected -1.0 to 68.0, Jan +3.5 to 69.0.
1000 ETJan construction spending expected +0.6% m/m, Dec -0.2% m/m.
1030 ETEIA Weekly Petroleum Status Report.
1300 ETDallas Fed President Robert Kaplan (voter) speaks at Paul Quinn College in Dallas, TX.
1400 ETFed Beige Book.
1800 ETFed Governor Lael Brainard speaks on the economic outlook and monetary policy at Harvard Universitys John F. Kennedy School of Government.
n/aFeb total vehicle sales expected 17.70 million, Jan 17.48 million. Feb domestic vehicle sales expected 13.65 million, Jan 13.60 million.
Thursday, Mar 2
US0730 ETFeb Challenger job cuts, Jan -38.8% y/y.
0830 ETWeekly initial unemployment claims expected +1,000 to 245,000, previous +6,000 to 244,000. Weekly continuing claims expected unch at 2.060 million, previous -17,000 to 2.060 million.
0830 ETUSDA weekly Export Sales.
1100 ETTreasury announces amount of 3-year T-notes (previous $24 billion), 10-year T-notes (previous $23 billion) and 30-year T-bonds (previous $15 billion) to be auctioned Mar 7-9.
1900 ETCleveland Fed President Loretta Mester (non-voter) speaks on leadership at the Athena Center for Leadership Studies at Barnard College in New York.
U.S. STOCK CALENDAR03/01/2017
CompanyTickerTimeEvent DescriptionPeriodEstimate
Mallinckrodt PLCMNK US4:30Annual General MeetingY 2017
Lowe's Cos IncLOW USBf-mktQ4 2017 Earnings ReleaseQ4 20170.785
Dollar Tree IncDLTR USBf-mktQ4 2017 Earnings ReleaseQ4 20171.321
Best Buy Co IncBBY US7:00Q4 2017 Earnings ReleaseQ4 20171.667
Best Buy Co IncBBY US8:00Q4 2017 Earnings CallQ4 2017
Honeywell International IncHON US9:00Investor ConferenceY 2017
Hershey Co/TheHSY US9:00Analyst DayY 2017
Lowe's Cos IncLOW US9:00Q4 2017 Earnings CallQ4 2017
Universal Health Services IncUHS US9:00Q4 2016 Earnings CallQ4 2016
Dollar Tree IncDLTR US9:00Q4 2017 Earnings CallQ4 2017
TransDigm Group IncTDG US9:00Annual General MeetingY 2017
Ford Motor CoF US9:15February 2017 Sales and Revenue Release2017
Exxon Mobil CorpXOM US9:30Analyst MeetingY 2017
Ford Motor CoF US10:00February 2017 Sales and Revenue Call2017
Mylan NVMYL US13:00Investor DayY 2017
Monster Beverage CorpMNST US17:00Q4 2016 Earnings CallQ4 2016
Broadcom LtdAVGO US17:00Q1 2017 Earnings CallQ1 2017
Monster Beverage CorpMNST USAft-mktQ4 2016 Earnings ReleaseQ4 20160.302
Broadcom LtdAVGO USAft-mktQ1 2017 Earnings ReleaseQ1 20173.474
Equifax IncEFX USInvestor MeetingY 2017
Helmerich & Payne IncHP USAnnual General Meeting
McDonald's CorpMCD USInvestor MeetingY 2017
Mylan NVMYL USQ4 2016 Earnings ReleaseQ4 20161.422